Breaking News: A True No-Income & No-Employment Mortgage Product Arrives in the Temecula Valley
For nearly two decades, the words “no income” and “stated income” have reminded many people of the 2008 housing crisis. Today, however, a very limited number of specialty mortgage investors have introduced products that revisit alternative underwriting—but with significantly different safeguards than those seen before the 2008 financial crisis. Looking Back at 2008 Before the […]
What Mortgage Products Are Available for Manufactured Homes on Permanent Foundations in the Temecula Valley?
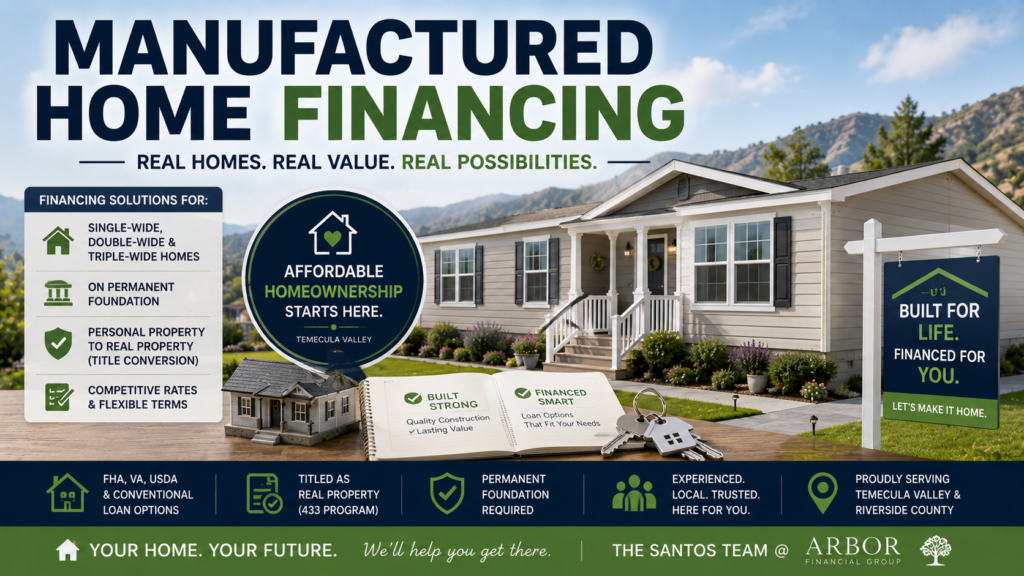
Manufactured Homes have become an increasingly popular housing option throughout the Temecula Valley, especially in Wine Country, Aguanga, Anza, and other rural communities where buyers can own acreage at a more affordable price than with traditional site-built homes. Fortunately, several financing options are available—but eligibility depends largely on how you intend to occupy the property. […]
CALHFA MyHome + ZIP: A Popular Down Payment Assistance Program in the Temecula Valley
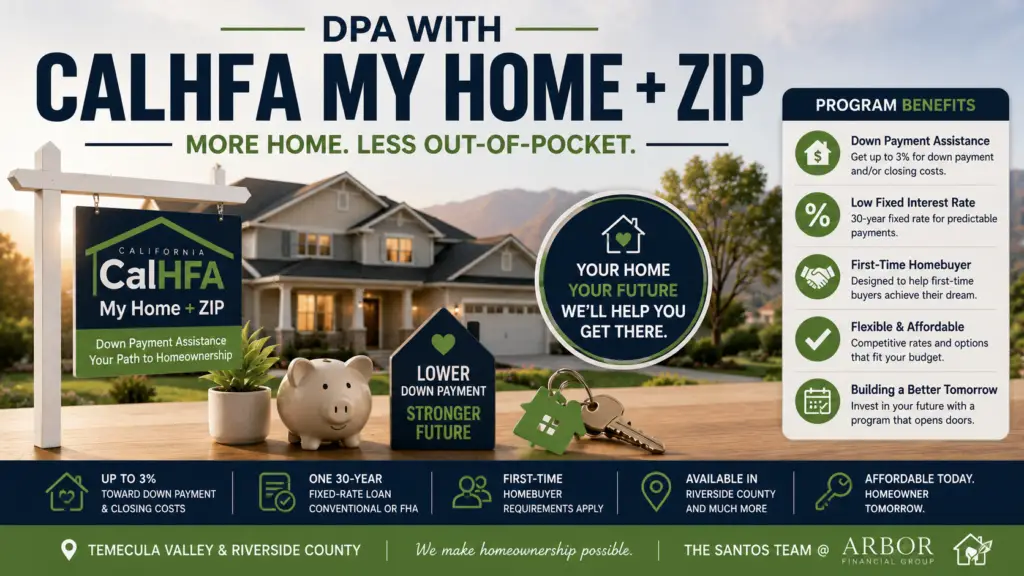
For many first-time homebuyers, saving for a down payment is the biggest obstacle to purchasing a home. One of California’s most well-known solutions is the California Housing Finance Agency (CalHFA) MyHome + ZIP program, which combines down payment assistance with help covering many of the upfront closing costs. For eligible buyers in the Temecula Valley, […]
Mortgage Credit Adjustment #10: Do You Need Credit to Obtain Credit for a Mortgage in the Temecula Valley?

One of the most common questions I hear is: “Why do I need credit to obtain credit?” It’s a fair question, and in many ways, it feels backwards. Today’s mortgage world depends heavily on historical credit data. If you’ve never borrowed money or have very little documented credit history, qualifying for a mortgage can actually […]
Mortgage Credit Adjustment #9: The Good, the Bad & the Ugly of Co-Signing for a Mortgage in the Temecula Valley

Co-signing for a mortgage is one of the most generous things someone can do for a family member. It can also be one of the riskiest financial decisions they ever make. As a loan officer, this often leads to what I call “the uncomfortable conversation.” The Uncomfortable Conversation Here’s how it usually starts. A homebuyer […]
Mortgage Credit Adjustment #8: Building Credit from Scratch & Understanding Manual Underwriting in the Temecula Valley

Have you ever wondered how someone with little or no credit history qualifies for a mortgage? Believe it or not, there was a time when almost every mortgage was underwritten without the automated credit scoring systems we use today. A Look Back at Mortgage Lending in the 1990s When I entered the mortgage industry in […]
Mortgage Credit Adjustment #7: Debt Utilization, FICO & VantageScore for Mortgages in the Temecula Valley

When most people think about their credit score, they usually ask one simple question: “Do I pay my bills on time?” For decades, that was the primary way lenders judged creditworthiness. While payment history is still typically the single most important factor in mortgage lending, modern credit scoring also places significant emphasis on debt utilization. […]
Mortgage Credit Adjustment #6: How Medical Collections, Student Loan Collections, Charge-Offs, Tax Liens, Judgments, and Mortgage Credit Impact Mortgage Qualification in the Temecula Valley

Not every credit issue affects your mortgage application the same way. While late credit card payments, bankruptcies, and foreclosures receive most of the attention, several other credit events can significantly impact your ability to qualify for a home loan. And types of mortgages also play a role. For instance, Jumbo Financing has a pretty strict […]
Mortgage Credit Adjustment #5: How Rapid Rescores Impact Mortgage Qualification in the Temecula Valley

One of the most powerful tools available during the mortgage process is a Rapid Rescore. When used correctly, it can quickly update a borrower’s mortgage credit report and, in some cases, improve qualification or interest rate options. However, a rapid rescore is not credit repair, and there are never guarantees that your score will increase. […]
Mortgage Credit Series Adjustment #4: Authorized User Accounts and Mortgage Qualification in the Temecula Valley

Authorized user accounts can be an excellent tool for building credit—but they can also create unexpected issues when qualifying for a mortgage. Understanding how lenders view authorized user accounts can help you avoid surprises during underwriting. What Is an Authorized User Account? An authorized user is someone who is added to another person’s credit card […]
Mortgage Credit Adjustment #3: Understanding Credit Inquiries in the Temecula Valley

One of the biggest myths in mortgage lending is that checking your credit or shopping for a mortgage will dramatically lower your credit score. Fortunately, that’s generally not how mortgage credit scoring works. Understanding how inquiries work can help you shop for the best loan without unnecessary concern. What Is a Credit Inquiry? A hard […]
Mortgage Credit Adjustment #2: Understanding Disputed Accounts in the Temecula Valley

Disputed accounts are one of the most misunderstood topics in mortgage lending. Many borrowers are surprised to learn that disputing an account before applying for a mortgage can actually delay or even prevent loan approval. Understanding why mortgage lenders care about disputed accounts begins with the aftermath of the 2008 housing crisis. How Disputed Accounts […]
Mortgage Credit Adjustment #1: Paying Off Debt Before Buying a Home in the Temecula Valley
One of the most common questions I hear is, “Should I pay off all my debt before applying for a mortgage?” The answer surprises many buyers: Not always. Paying off debt can improve your financial picture, but paying off—or worse, closing—credit accounts at the wrong time can actually lower your mortgage credit score. Why You […]
Financing Manufactured Homes in the Temecula Valley: What Buyers Need to Know
Manufactured housing provides an affordable path to homeownership throughout the Temecula Valley and surrounding communities. Whether you’re looking at a home on acreage in Aguanga or a manufactured home in a resident-owned community, understanding the different types of factory-built housing is the first step toward choosing the right financing. This type of property is highly […]
Reverse Mortgages in the Temecula Valley: Separating Myths from Reality
One of the biggest misconceptions about reverse mortgages is that the government or the lender wants to take your home. It’s a myth that has persisted for years, yet it doesn’t reflect how most reverse mortgages in the United States actually work. Today, approximately 95% of reverse mortgages originated nationwide are Home Equity Conversion Mortgages […]
How Jumbo Financing Applies to Real Estate in the Temecula Valley
The Temecula Valley has evolved into one of Southern California’s premier luxury home markets. From the rolling vineyards of Temecula Wine Country to the custom estates of De Luz, Meadowview, Santiago Estates, La Cresta, Canyon Lake, Morgan Hill, Wolf Creek, and other upscale communities, Jumbo financing has become part of everyday real estate. As home […]
The Impact of USDA Financing on Real Estate in the Temecula Valley
For many homebuyers, USDA financing is one of the best-kept secrets in mortgage lending. Offering 100% financing and lower mortgage insurance costs than many other loan programs, USDA loans have helped thousands of families become homeowners in rural America. While USDA eligibility within the Temecula Valley has become much more limited over the years, the […]
How Credit Works When You Apply for a Mortgage in the Temecula Valley

One of the first questions homebuyers ask is, “What credit score do I need to qualify for a mortgage?” While your credit score is important, many borrowers don’t realize there’s an entire credit reporting system working behind the scenes. Understanding how mortgage credit works can help you prepare for a smoother home loan process. A […]
The Doors That Non-QM Financing Opens in The Temecula Valley
For decades, qualifying for a mortgage meant fitting into a traditional lending box. W-2 employees with steady paychecks, predictable tax returns, and standard debt ratios generally had the easiest path to homeownership. Then from the late 1990’s to 2008, sub-prime allowed the wheels to fall off with 80/20 Stated Income Financing. And eventually became one […]
Why Non-QM Financing Has Grown in the Temecula Valley Since 2021
For years, most homebuyers qualified for a mortgage using traditional documentation such as W-2s, tax returns, and paycheck income. While those programs continue to serve millions of borrowers, today’s workforce has changed dramatically. More Americans are self-employed, own small businesses, invest in real estate, or earn income in ways that don’t always fit conventional lending […]
Things Buyers Need to Know About Property Taxes in the Temecula Valley
Property taxes are one of the largest ongoing costs of homeownership, yet many buyers don’t fully understand how they’re calculated. Whether you’re purchasing your first home or your fifth, understanding California’s Property Tax System can help you budget accurately and avoid unexpected tax bills after closing. And drilling down further, understanding how property taxes work […]
How The Santos Team at Arbor Financial Group Can Move Faster Than TRID Timelines in the Temecula Valley
When buying a home, one of the most common questions borrowers ask is, “How quickly can we close?” The answer depends on several factors, including the loan program, appraisal timing, title work, underwriting, and of course the selling-party. However, one timeline that every mortgage lender must follow is known as TRID. Understanding TRID helps explain […]
How California Community Property Rules Impact Mortgage Qualification in the Temecula Valley
California is one of only a handful of community property states and those laws can affect how you qualify for a mortgage. Whether you’re buying in Temecula, Murrieta, Menifee, Winchester, or the surrounding communities, understanding these rules before applying can help prevent surprises during underwriting. Especially because our areas have a higher concentration of VA […]
Types of Appraisals Used for Mortgages in the Temecula Valley
Most homebuyers simply hear the words, “The appraisal has been ordered.” In reality, there are several different appraisal report types used throughout the mortgage process. Depending on the property, loan program, and transaction, your lender may require a specialized appraisal or follow-up inspection. Understanding the different appraisal products can help make the mortgage process much […]
Understanding Residential Appraisals in The Temecula Valley
One of the most important steps in the mortgage process is the residential appraisal. Whether you’re purchasing or refinancing a home in Temecula, Murrieta, Menifee, Winchester, or the surrounding communities, the appraisal helps determine whether the property’s market value supports the requested loan amount and sales price for a purchase. While buyers often think an […]
The Life-Cycle of the Residential Appraisal Process in the Temecula Valley
For many homebuyers, the appraisal is one of the biggest milestones in the mortgage process. While most borrowers know an appraiser visits the property, few understand everything that happens before and after the inspection. Here’s a step-by-step look at the life of a residential appraisal in the Temecula Valley. Step 1: The Appraisal Is Ordered […]
Conventional Financing in the Temecula Valley: Understanding Mortgage Recasting
Many homeowners have heard about refinancing, but far fewer know about another option that may reduce a monthly mortgage payment without replacing the existing loan—a mortgage recast. For Conventional homeowners in the Temecula Valley, a recast can be an effective financial planning tool after closing. What Is a Mortgage Recast? A mortgage recast, sometimes called […]
Conventional Financing in the Temecula Valley: Pillar Three – Understanding Assets
The third pillar of qualifying for a Conventional Mortgage is assets. While your credit determines your financing options and your income determines how much you can qualify for, your assets demonstrate that you have the funds necessary to complete the transaction. Lenders review assets to verify the source of your down payment, closing costs, reserves […]
Conventional Financing in the Temecula Valley: Pillar Two – Understanding Income
After credit, income is the second pillar of qualifying for a Conventional Mortgage. Whether you’re a W-2 employee, self-employed business owner, or earn bonus or commission income, Fannie Mae and Freddie Mac have established guidelines to determine whether your income is stable, predictable, and likely to continue. Who Are Fannie Mae and Freddie Mac? Most […]
Conventional Financing in the Temecula Valley: Pillar One – Understanding Credit
Credit is the first pillar of qualifying for a Conventional Mortgage. While income and assets are equally important, your credit profile often determines not only whether you qualify, but also your interest rate, mortgage insurance costs, and overall loan pricing. How Conventional Credit Scores Are Used Mortgage lenders obtain a tri-merge credit report using Experian, […]
Why Conventional Financing Is the Most Popular Mortgage in Temecula Valley
When homebuyers begin exploring mortgage options, they often hear about FHA and VA loans. While both programs offer excellent benefits, Conventional Financing remains the most widely used mortgage program in the United States and for good reason. Conventional Financing consists of Fannie Mae (FNMA) and Freddie Mac (FHLMC). Both under government control, as of 2026. […]
Things to Know About VA Appraisals in the Temecula Valley
A VA appraisal is more than just an opinion of a home’s value—it’s designed to help protect both the veteran and the Department of Veterans Affairs. While the appraisal process shares many similarities with Conventional and FHA financing, VA loans include several unique features that every homebuyer should understand before making an offer. VA Panel […]
VA Loans in Temecula Valley: Why There’s No Monthly Mortgage Insurance
One of the biggest financial advantages of a VA home loan is that eligible veterans can purchase a home with no down payment and no monthly mortgage insurance (MI). This benefit often results in the lowest monthly payment available among today’s 100% financing options and even cheaper than FHA with a down payment. Many buyers […]
VA Loans in Temecula Valley: Understanding of Assets (Pillar Three)
In our previous articles, we explored Pillar One (Credit) and Pillar Two (Income). The third pillar of VA mortgage qualification is Assets—the funds needed to complete your home purchase. One of the greatest advantages of VA financing is that eligible borrowers can often purchase a home with no down payment, making it one of the […]
VA Loans in Temecula Valley: Understanding VA Income (Pillar Two)
One of the greatest advantages of VA financing is its flexibility when qualifying income. While the Department of Veterans Affairs offers some of the most borrower-friendly mortgage guidelines available, lenders must still verify that every borrower has stable, reliable income that is expected to continue. Whether you’re active duty, retired from military service, or have […]
VA Mortgage Credit Requirements in Temecula Valley: Understanding Pillar One (Credit)
In our previous VA overview, we discussed the three pillars of mortgage qualification: Credit, Income, and Assets. While all three matter, Credit is often where borrowers have the most questions. We will call this Pillar One. The good news is that VA financing is one of the most forgiving mortgage programs available. The VA’s primary […]
VA Loans in Temecula Valley: Understanding the Three Pillars of Qualification (Credit, Income, Assets)
VA financing is one of the most powerful mortgage benefits available to eligible veterans, active-duty service members, reservists, National Guard members, and certain surviving spouses. Backed by the U.S. Department of Veterans Affairs, VA loans offer flexible guidelines, no down payment requirements in most cases to $1,500,000 financed in Riverside County, and no monthly mortgage […]
Why VA Loans Remain a Powerful Home Financing Option in Temecula Valley
For generations, VA Home Loans have helped military service members, veterans, reservists, and eligible surviving spouses achieve homeownership with some of the most favorable financing terms available. In Temecula Valley, where many military families choose to live while serving or after retirement, VA financing continues to be one of the most valuable mortgage benefits earned […]
FHA Assets Requirements in Temecula Valley: What Potential Buyers Need to Understand (Pillar Three)
In previous articles, we discussed Pillar One (Credit) and Pillar Two (Income). The third pillar of FHA mortgage qualification is Assets. Assets represent the funds available to complete your home purchase. The good news is that FHA financing is one of the most flexible mortgage programs available when it comes to down payment and asset […]
FHA Income Requirements in Temecula Valley: What Homebuyers Need to Know (Pillar Two)
FHA financing continues to be one of the most popular mortgage options for homebuyers throughout Temecula Valley because of its flexible qualification guidelines. However, regardless of Pillar One — Credit Score or Pillar Three — Down Payment, every FHA borrower must demonstrate stable and reliable income (Pillar Two) that is expected to continue. FHA underwriters […]